Market overview and structural significance of the Warehouse Slotting Optimization Software Market
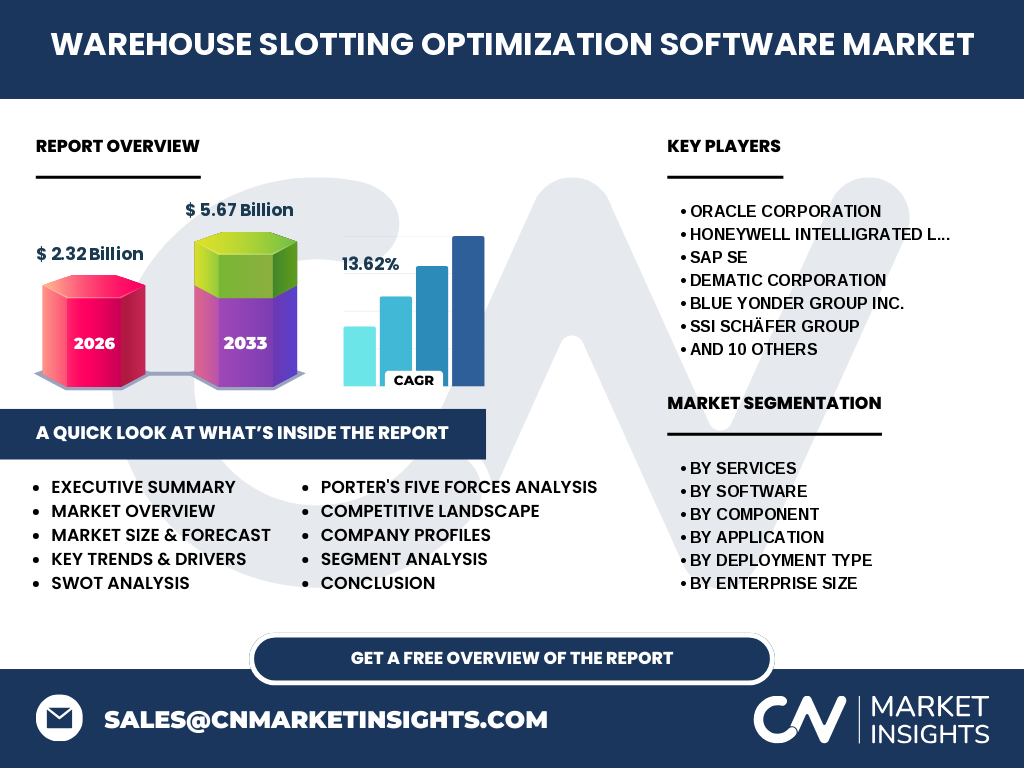
The Warehouse Slotting Optimization Software Market is valued at 2.32 Billion in 2026, serving as the foundational computational layer for modern distribution centers. Our analysis indicates that as supply chains grapple with SKU proliferation and labor scarcity near major hubs like the Port of Los Angeles, advanced algorithms dynamically assign inventory locations to minimize travel times, reduce ergonomic strain, and maximize cubic storage utilization.
What structural growth drivers and market restraints shape the Warehouse Slotting Optimization Software Market?
Structural growth drivers include soaring e-commerce fulfillment demands and high real estate lease rates, while primary restraints involve high initial integration costs with legacy Warehouse Management Systems. Companies like Manhattan Associates Inc. and Blue Yonder Group Inc. mitigate these barriers by offering cloud-based configurations that accelerate time-to-value for third-party logistics providers navigating strict OSHA ergonomic compliance mandates.
Emerging trends and transformation patterns across the Warehouse Slotting Optimization Software Market industry trends
The shift toward AI-driven continuous slotting represents a major inflection point, moving operations away from static quarterly re-slotting. Based on our research, vendors such as Lucas Systems Inc. and Dematic Corporation integrate real-time demand forecasting to automatically adjust pick-face locations based on fluctuating velocity profiles driven by seasonal retail surges.
How did the pandemic alter the trajectory of the Warehouse Slotting Optimization Software Market analysis?
The COVID-19 pandemic permanently altered fulfillment priorities, creating an unprecedented surge in digital orders that overwhelmed manual slotting strategies. Our research shows this disruption catalyzed enterprise migration toward automated inventory analytics, as firms sought resilient software solutions from providers like TECSYS Inc. and Generix Group S.A. to manage severe workforce absenteeism.
Competitive benchmarking and market concentration within the Warehouse Slotting Optimization Software Market
The competitive landscape features a mix of supply chain suites and specialized point solutions, with enterprise giants like Oracle Corporation, SAP SE, and Honeywell Intelligrated LLC commanding significant market share. Strategic dynamics heavily favor ecosystem integration, where incumbents leverage existing ERP footprints to bundle advanced slotting modules directly into core warehouse operations.
Executive summary of core findings for the Warehouse Slotting Optimization Software Market
Our executive analysis projects the market to expand from 2.32 Billion in 2026 to reach 5.67 Billion by 2033, achieving a robust CAGR of 13.62%. This acceleration is underpinned by widespread adoption across automated fulfillment centers seeking maximum throughput efficiency in response to escalating labor costs and rising consumer expectations for same-day delivery.
Warehouse Slotting Optimization Software Market market size and financial forecast from 2027 to 2033
The data suggests sustained double-digit expansion, scaling from the 2026 baseline of 2.32 Billion to culminate at 5.67 Billion by the end of 2033. This trajectory reflects a steady 13.62% CAGR, fueled by rapid digitization within cold-chain logistics, automotive manufacturing parts distribution, and omnichannel retail fulfillment centers globally.
Segmentation analysis across services, software, component, application, deployment, enterprise size, and end-user verticals
Market segmentation spans multiple categories: By Component (Software and Services); By Software (Inventory Optimization, Slotting Analysis, Warehouse Analytics, Order Picking Optimization, Demand Forecasting, Space Utilization); By Services (Consulting, Implementation, Maintenance, Training, Managed, Customization); By Application (Inventory Management, Order Fulfillment, Workforce Management, Reporting); By Deployment (On-Premise, Cloud-Based, Hybrid); By Enterprise Size (SMEs, Large Enterprises); and By End User (Retail/E-commerce, Manufacturing, 3PL, Food/Beverage, Healthcare/Pharma, Automotive, Consumer Goods).
Geographic distribution and regional performance across the Warehouse Slotting Optimization Software Market
Regional performance varies significantly, with North America leading adoption due to concentrated high-throughput distribution hubs and advanced retail infrastructure. Meanwhile, Asia-Pacific represents the fastest-growing regional market, driven by rapid industrialization, expanding third-party logistics networks in Southeast Asia, and massive investments in automated fulfillment infrastructure by innovators like SSI SCHÄFER Group and Mecalux S.A.
In-depth regional review of key operational constraints and localized adoption drivers
Regional adoption is heavily dictated by labor availability and real estate pricing pressures. In densely populated European markets, strict urban zoning laws and high land costs mandate maximum cubic utilization, compelling facilities to deploy software solutions from Ingka Group and OPEX Corporation to optimize vertical space within constrained footprints.
Company profiles and strategic positioning of leading innovators in the ecosystem
Market leaders utilize distinct competitive strategies to capture share. Deposco Inc. and Logiwa Inc. focus heavily on agile, cloud-native deployments tailored for mid-market e-commerce sellers, whereas Epicor Software Corporation targets discrete manufacturers, ensuring slotting algorithms account for heavy industrial components and complex bill-of-materials staging requirements.
Porter's Five Forces assessment of competitive intensity within the industry
Our analysis of Porter's forces reveals moderate-to-high competitive rivalry driven by frequent product feature parity among mid-tier vendors. Supplier power remains low given the abundance of alternative algorithms, while buyer power is moderate-to-high as large 3PL providers demand highly customized pricing models and seamless integration with proprietary automation hardware.
SWOT analysis highlighting core strengths, vulnerabilities, opportunities, and strategic threats
Key strengths include high ROI through reduced travel time, while weaknesses center on complex data cleansing prerequisites. Opportunities emerge in generative AI integration for predictive slotting, whereas threats involve macroeconomic volatility delaying capital expenditure approvals for large-scale enterprise software upgrades.
Value chain analysis detailing the flow from raw algorithmic development to end-user deployment
The value chain originates with core data science research and algorithmic modeling, flowing through software developers and cloud infrastructure providers before reaching systems integrators and end-users in retail, automotive, and healthcare sectors. Optimization software acts as the critical brain connecting warehouse automation hardware like conveyors and AS/RS systems to enterprise resource planning platforms.
Investment insights and high-potential areas for strategic portfolio allocation
High-potential investment areas center on cloud-native managed services and hybrid deployment architectures that lower entry barriers for small and medium enterprises. Investors should target vendors with proprietary machine learning capabilities capable of automating slotting adjustments without requiring dedicated on-site industrial engineers.
Conclusion and strategic takeaways for industry stakeholders
Achieving market leadership requires transitioning from static slotting rules to continuous, AI-driven optimization models. With the market projected to reach 5.67 Billion by 2033 at a 13.62% CAGR, stakeholders must prioritize seamless ERP integration, user-friendly mobile analytics, and adaptable deployment models to capture expanding demand across retail and third-party logistics.
Research methodology used to triangulate baseline estimates and forecast metrics
Our rigorous methodology triangulates data by combining primary stakeholder interviews with warehouse directors and supply chain VPs, secondary trade registry data from major global shipping ports, and macroeconomic indicators tracking global industrial automation spending, ensuring high-fidelity market sizing and growth projections.
Scope of the report, coverage parameters, and analytical limitations
This report covers global deployment trends across seven core end-user verticals and six distinct software categories, evaluating enterprise software revenue from 2026 through 2033. Limitations include the exclusion of pure-play hardware manufacturing revenue that is not directly tied to software licensing, implementation, or ongoing maintenance services.
Recent developments, corporate partnerships, and product launches in the sector
Recent industry momentum is defined by strategic acquisitions and cloud-native product launches aimed at enhancing real-time inventory visibility. Major market participants continue to forge deep partnerships with industrial robotics manufacturers, ensuring that slotting software seamlessly coordinates both human pickers and autonomous mobile robots within high-density fulfillment environments.